Direct answer
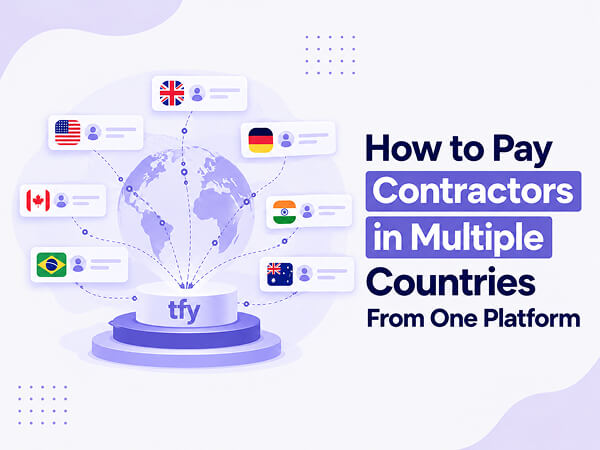
The most reliable way to pay contractors in multiple countries from one platform is to centralise the full contractor payroll workflow - contractor data, invoices or approved work, payment approvals, funding, foreign exchange, payout execution and reconciliation - while still using the appropriate payment rail for each destination. The platform should reduce operational fragmentation without pretending that every country, currency or contractor can be handled identically.
Key takeaways
- One platform should centralise control, not force every country onto one payment rail. Local bank rails, SEPA, SWIFT, wallets or other methods may still differ by destination.
- The hardest part is rarely pressing “pay”. It is keeping contractor records, approvals, beneficiary details, FX, fees, payment status and accounting evidence consistent across countries.
- Finance teams should compare the total cost of payment - platform fee, FX spread, transfer fee, intermediary deductions, recipient fee and exception handling - rather than a headline transfer price.
- Country coverage needs to be tested at the currency-and-rail level. A provider may support a country but not every payout currency, banking corridor or contractor type.
- For TFY, the relevant proposition is broader than a payment processor: TFY publicly positions its Contractor Payroll / Contractor of Record service around one contract, classification and compliance support, multi-currency payments, automated billing and contractor management across 184+ countries.
What “one platform” should actually consolidate
Layer |
What should be centralised |
What may still vary |
Why it matters |
|
Contractor record |
Identity, contract, country, currency, tax and payout data |
Local documentation requirements |
Creates one source of truth |
|
Payable event |
Invoice, milestone, timesheet or approved fee |
Invoice rules and tax evidence |
Prevents ad-hoc payments |
|
Approvals |
Roles, thresholds, cost centres, segregation of duties |
Local or entity-specific approvers |
Creates control before funds move |
|
Funding & FX |
Funding request, conversion record, fee visibility |
Funding currency and FX route |
Makes cost visible |
|
Payout execution |
Status, beneficiary details, settlement reference |
Local rail, SWIFT, SEPA, wallet or other method |
Balances reach with reliability |
|
Reconciliation |
Invoice-to-payment match, fees, FX, ledger evidence |
Accounting treatment and tax reporting |
Turns payment into an auditable process |
What does it mean to pay contractors from one platform?
A multi-country contractor-payment platform is a control layer that lets a company manage payments to contractors in several jurisdictions through one operating workflow. It does not mean the underlying money movement is identical everywhere. The provider may route payments through different banking partners, local clearing systems, correspondent banks or wallet infrastructure depending on the destination.
That distinction matters. A good platform standardises what the company should control centrally - data, approvals, funding, visibility, records and exceptions - while preserving the flexibility required by local payment infrastructure.
Contractor payroll is more than a payment rail
As TFY explains in What Is Contractor Payroll? A Complete Guide, contractor payroll is the controlled process used to validate amounts owed, approve payments, handle currencies and fees, reconcile transactions and retain the evidence around those payments. A platform that only moves money may solve the final step while leaving the operating burden elsewhere.
How paying contractors across multiple countries works
A scalable model usually follows the same sequence even when the payout method changes from country to country.
1. Establish the contractor record
Capture the legal or business name, country, engagement entity, contract, payment currency, beneficiary details, tax documentation and internal owner. The record should be complete before the first payable event is approved.
2. Confirm contractor status and engagement terms
The contract label does not decide worker status. Classification should reflect the real relationship and applicable local law. This is particularly important when the workforce spans countries with different employment-status tests.
3. Create the payable event
The amount may arise from an invoice, approved timesheet, milestone or fixed recurring fee. The platform should connect the amount to the governing contract and the evidence of work.
4. Validate and approve
Check the contractor, amount, currency, cost centre, supporting evidence and approval authority. Separate the person validating the payable item from the person releasing funds where practical.
5. Fund the platform or payment batch
The company typically funds a consolidated amount or payment batch. Treasury should know the funding currency, cut-off time, cash requirement and whether funds need to be prefunded.
6. Apply FX where required
If the company funds in one currency and contractors receive another, conversion takes place. The important questions are when the rate is set, how the spread is disclosed, whether it can change before settlement and which party bears conversion costs.
7. Route each payout through the appropriate rail
A payment to a euro account in the SEPA area may follow a different rail from a payment to another market using SWIFT or a domestic partner. The platform should hide operational fragmentation from the client without hiding the status or cost of each transaction.
8. Monitor failures and exceptions
Invalid bank details, account restrictions, compliance reviews, rejected transactions, closed accounts and beneficiary-name mismatches can interrupt settlement. The platform should surface the reason, owner and next action.
9. Reconcile each payment
Match the contractor, invoice or payable item, gross amount, FX, fees, settlement amount and payment reference. Reconciliation is essential when a single funding event produces many individual contractor payouts.
10. Retain records and reassess
Keep contract, classification, identity, tax, invoice, approval and payment records. Reassess long-running engagements when the working relationship changes.
Which payment rails are used for multi-country contractor payments?
Payment route |
Typical strength |
Trade-off |
Best fit |
|
Domestic / local bank rail |
Can improve local delivery and reduce dependence on correspondent chains |
Availability and cut-offs vary by market |
Recurring payouts in supported markets |
| SEPA |
Standardised euro payments across the SEPA area |
Euro-focused and subject to participant/bank rules |
EUR contractor payouts in SEPA |
|
SWIFT |
Broad international reach |
Intermediary banks, deductions and timing can be less predictable |
Corridors without a suitable local rail |
|
Digital wallet / payment account |
Useful where contractors prefer supported digital accounts |
Provider, country and account limits vary |
Contractors already using the supported ecosystem |
| Crypto / stablecoin payout |
Potentially useful in selected corridors and for contractors who choose it |
Regulatory, tax, custody and operational considerations are material |
Optional use cases where lawful and supported |
What does it cost to pay contractors in multiple countries?
The relevant number is total landed cost, not the transfer fee shown on a pricing page. A low-cost transfer can still become expensive if Finance absorbs poor FX, intermediary deductions, recipient-bank charges, failed-payment handling or manual reconciliation.
- Platform or contractor-payroll fee
- FX spread or conversion fee
- Bank or payment-rail fee
- Intermediary/correspondent-bank deductions where applicable
- Recipient-bank or wallet charges
- Failed-payment or return costs
- Internal operational cost of onboarding, approvals, support and reconciliation
For procurement, the better question is: “What is the expected all-in cost for this contractor to receive the agreed amount in this destination, and which components can vary?”
Why international contractor payments fail
Incorrect beneficiary data
Names, account numbers, routing codes, bank addresses or beneficiary types may be incomplete or inconsistent.
Unsupported route or currency
“Country supported” does not necessarily mean every currency, account type or payout rail is available.
Compliance review
Financial institutions and payment providers may pause or reject transactions when identity, sanctions or transaction-risk controls require review.
Banking-chain deductions
Cross-border wires can pass through intermediary institutions. The amount received can differ from the amount sent depending on fee arrangements and the chain used.
Funding or cut-off issues
Late prefunding, bank holidays, local cut-offs and time-zone differences can move settlement into the next processing window.
Contractor changes not reflected in the system
A changed bank account, legal entity or tax status can create exceptions if the contractor record is stale.
Compliance controls that sit around the payment
Payments infrastructure and workforce compliance overlap, but they are not the same thing. A platform should make it easier to evidence both without suggesting that moving money automatically resolves worker status, tax or local employment questions.
For payment-system controls, the FATF Recommendations set international standards for anti-money-laundering and counter-terrorist-financing measures, including customer due diligence and payment-transparency expectations implemented through national rules.
For US contractor tax administration, the IRS guidance on forms and taxes for independent contractors explains the use of Form W-9 and Form 1099-NEC in relevant US situations.
In the UK, businesses using personal-service companies should also consider the HMRC guidance on off-payroll working (IR35), because the payment workflow does not override the underlying employment-status analysis.
Example: 120 contractors across 14 countries
Consider a mid-sized technology business with 120 contractors spread across 14 countries. Finance funds in GBP and EUR. Contractors invoice in a mixture of EUR, USD and local currencies. Some receive money through domestic bank rails, some through international wires, and a smaller group uses supported digital accounts.
Without a central platform, the company can end up with separate onboarding records, spreadsheets, invoice folders, banking portals and reconciliation files. The cost is not just administrative. It becomes difficult to answer basic questions: Who has been approved? Which contractors changed bank details? Which payments failed? What FX rate was applied? What did a country actually cost this month?
With a consolidated workflow, the company can approve one batch, fund according to the agreed model, allow the platform to route each payment appropriately, and reconcile the results against one contractor ledger. The underlying rails remain diverse; the operating control becomes consistent.
Selection checklist: choosing one platform for multi-country contractor payments
- Which countries are supported for contractor onboarding, and which are supported for payouts?
- Which payout currencies are available in each country?
- Which payment rails are used by destination - local bank rail, SEPA, SWIFT, wallet or another method?
- Can contractors choose a supported payout method without Finance creating separate processes?
- How are FX rates set, displayed and retained for audit?
- Can Finance see platform fees, payment fees and FX separately?
- How are failed payments, rejected beneficiary details and returns handled?
- Does the platform support maker-checker controls, approval thresholds and cost centres?
- Can one funding event be reconciled to individual contractor payouts?
- What contractor identity, KYC/KYB or sanctions controls are applied, and by which regulated parties?
- What tax documents can the workflow collect or retain where relevant?
- Can contractor classification, contract records and payment evidence be reviewed in one place?
- What accounting or API integrations are available?
- What is the data-export process if the company changes provider?
- What contractual responsibilities remain with the client?
Where TFY fits
TFY is most relevant when a company wants to consolidate international contractor operations rather than bolt another payment tool onto a fragmented process. Its public Contractor Payroll / Contractor of Record proposition combines contractor management, classification and compliance support, automated billing and invoicing, and multi-currency payments within one workforce platform.
TFY states that its Contractor Payroll / Contractor of Record service supports contractor operations in 184+ countries. Its pricing and product page also lists one contract with TFY for contractors, contractor classification and compliance management, global contractor payroll and payments, automated billing and invoicing, and multi-currency and crypto payments.
The commercial case is therefore not “one transfer method for the world”. It is one operational system through which HR, Finance and Legal can manage the contractor lifecycle while the underlying payout route varies by country and contractor preference.
For readers comparing the wider workflow, see How Does Contractor Payroll Work?. For currency-specific considerations, see Paying Global Contractors in Local Currency.
A simple decision tree
- If you pay only a handful of contractors in one or two countries, direct bank or payment-provider workflows may still be manageable.
- If you pay contractors across several countries and currencies, prioritise consolidated approvals, FX visibility, payout tracking and reconciliation.
- If classification, contracts and payment operations are becoming inseparable, evaluate a contractor-payroll or Contractor of Record model rather than a standalone transfer tool.
- If the role is actually employment rather than genuine independent contracting, assess an Employer of Record or direct-employment model instead.
Risks and limitations
One platform does not remove country-specific law
Contractor classification, tax documentation, payment restrictions and employment rules remain jurisdiction-specific.
Country coverage is not the same as currency coverage
Confirm the precise contractor type, payout currency, beneficiary account and rail for the markets you actually use.
Payment times can be estimates, not guarantees
Bank holidays, cut-offs, compliance reviews and correspondent banking can change settlement timing.
FX can obscure the real cost
Require visibility into the rate source, spread, fee and timing of conversion.
Centralisation creates concentration risk
A single provider can simplify operations, but the company should understand business-continuity arrangements, exportability of records and fallback payment processes.
A platform cannot cure misclassification
The actual working relationship must still support independent-contractor status under applicable rules.
Frequently asked questions
How can I pay contractors in multiple countries from one platform?
Use a contractor-payroll or workforce platform that centralises contractor records, approvals, funding, FX, payout instructions, payment status and reconciliation while routing each payment through an appropriate supported rail.
Can I make one payment and have the platform pay all my contractors?
Some contractor-payroll models support consolidated funding or billing, after which the provider executes individual contractor payouts. The exact funding structure, timing and contractual responsibility varies by provider.
What is the best way to pay international contractors?
There is no single best rail for every country. The best operating model is usually the one that combines reliable local coverage, transparent FX and fees, strong approval controls, exception handling and clean reconciliation.
Can contractors be paid in their local currency?
Often yes, where the provider supports the destination and currency. Confirm the exact currency, payout rail, bank-account requirements and whether the contractor receives the invoiced amount after fees.
How do companies pay hundreds of international contractors?
They typically standardise onboarding, contracts, invoice or timesheet approval, batch funding, FX, payout execution and reconciliation through a contractor-management or payroll platform rather than processing each contractor manually.
What happens if an international contractor payment fails?
The payment should move into an exception workflow showing the reason, status, affected amount and required correction. Common causes include invalid beneficiary details, unsupported accounts, compliance review or bank rejection.
Do international contractor payments require KYC or sanctions checks?
Financial institutions and regulated payment providers are subject to applicable identity, anti-money-laundering and sanctions obligations. The specific checks depend on jurisdiction, provider and payment route.
Is paying a contractor through a platform enough to make them an independent contractor?
No. Worker status depends on the facts of the relationship and applicable law. A payment platform or contract label does not by itself determine legal classification.
What should Finance ask a global contractor-payment provider?
Ask about country-and-currency coverage, payout rails, funding model, FX, all-in fees, approval controls, failures, reconciliation, tax and identity records, integrations, data export and contractual responsibility.